Hidden Charges on Inward Remittance: Every Fee Explained
TL;DR - Summary
- What are hidden charges on inward remittance? - These are fees and exchange-rate costs that reduce what you receive from an overseas payment and may not be clear upfront.
- What are the different layers of charges on an inward remittance? - Costs can include the sender’s transfer fee, intermediary deductions, the Indian bank’s forex markup and processing fee, and GST on taxable services.
- How much do hidden charges on a $5,000 inward remittance cost an Indian freelancer? - In the illustrative example below, fees, a 2% forex markup and GST reduce the recipient’s INR proceeds by ₹10,971.37. Actual costs vary.
- How do hidden charges on inward remittance affect FIRC and GST compliance? - Reconcile the invoice, remittance records and documented bank deductions. A lower net credit does not automatically mean a GST compliance failure.
- How does Skydo reduce hidden charges on inward remittance? - Skydo offers disclosed fees, zero forex markup and free remittance advice. Supported local collection avoids SWIFT collection fees; route-specific charges can still apply.
What Are Hidden Charges on Inward Remittance?
Hidden charges on inward remittance are fees and exchange-rate costs that reduce what an Indian recipient receives from an international payment. Some are disclosed separately; others are embedded in the conversion rate or deducted before credit.
Indian freelancers and exporters use inward remittances to receive payment from foreign clients for services or goods delivered. You expect the invoiced amount to arrive in full, but multiple parties in the payment chain take a cut.
Take an illustrative Pune-based graphic designer who invoices a UK client £1,000. At an assumed benchmark of ₹106 per pound, she expects ₹1,06,000, but receives ₹98,000. That ₹8,000 gap needs reconciliation: fees, the conversion rate and exchange-rate movement can all affect the final credit.
What Are the Different Layers of Charges on an Inward Remittance?
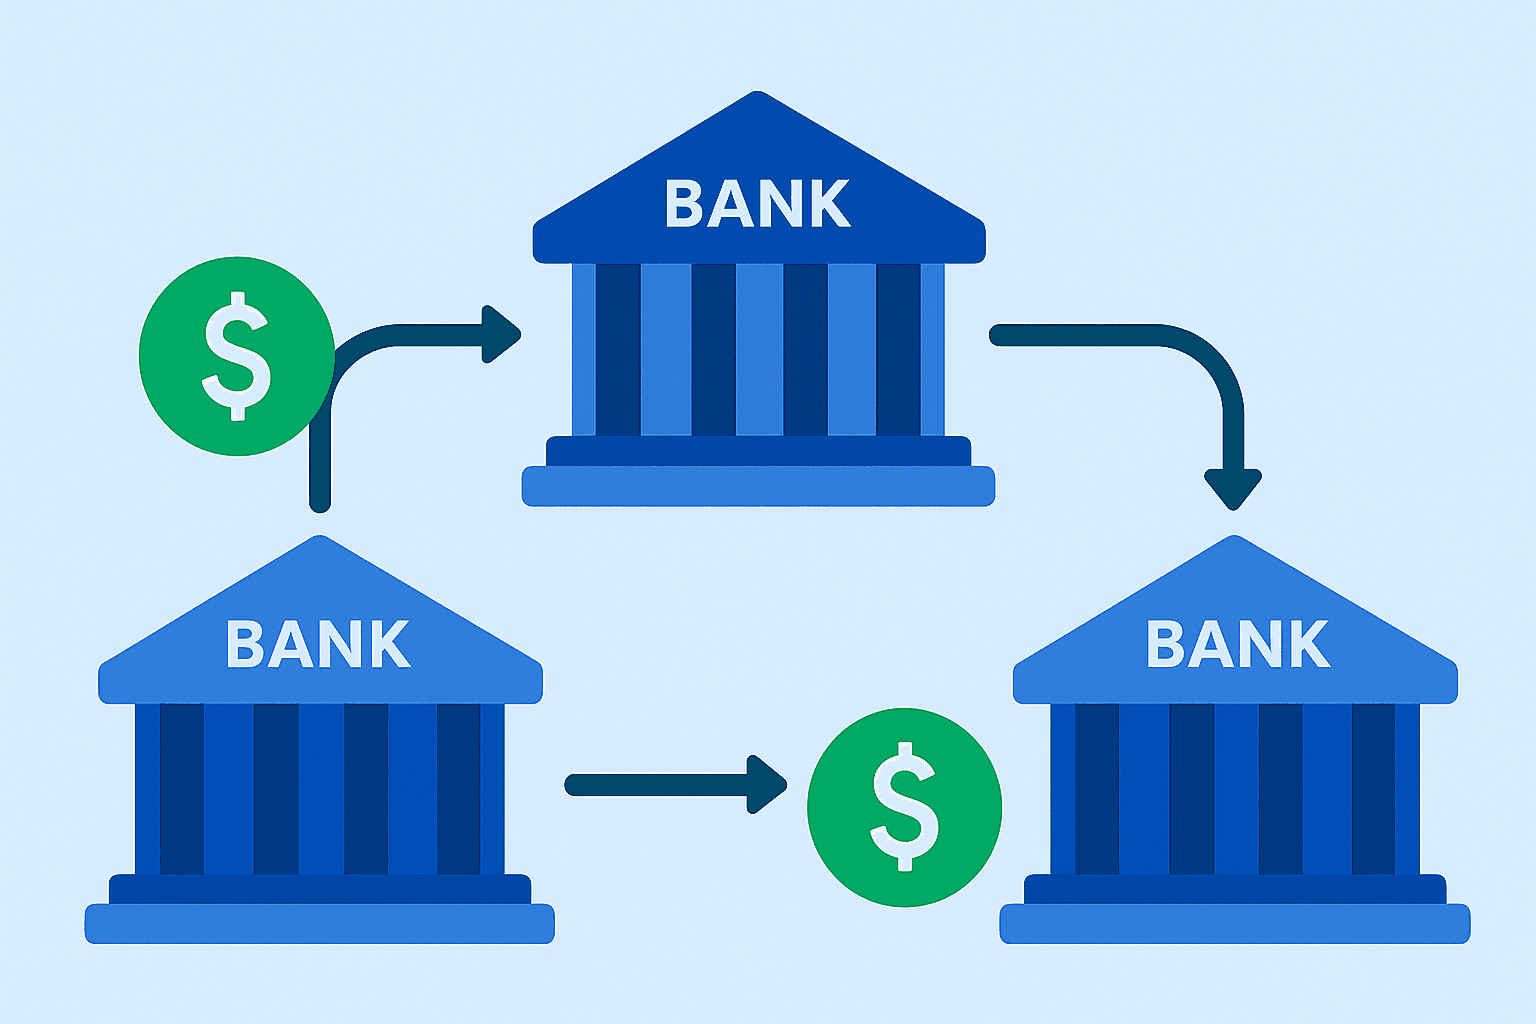
An inward remittance can involve four cost layers: the sender’s bank transfer fee, correspondent or intermediary bank deductions, the Indian bank’s forex markup, and its processing fee plus Goods and Services Tax (GST) on taxable services. A Society for Worldwide Interbank Financial Telecommunication (SWIFT) transfer does not necessarily incur every layer.
- Layer 1 (sender's bank SWIFT fee): Your foreign client's bank charges them a fee to initiate the SWIFT transfer. The sender typically pays this, but it does not guarantee the full amount arrives intact downstream.
- Layer 2 (correspondent/intermediary bank deductions): SWIFT payments may pass through correspondent banks. Charges depend on the route, bank tariffs and whether the sender or recipient bears them. Ask for the payment confirmation or trace rather than assuming a fixed fee per hop.
- Layer 3 (beneficiary bank forex markup): The Indian bank converts the foreign currency to Indian rupees (INR) using its own exchange rate. Compare that rate with a market benchmark at the time of conversion to estimate the spread. The spread is embedded in the rate rather than necessarily shown as a separate fee.
- Layer 4 (bank processing fee and GST): The Indian bank may charge a processing fee, generally subject to 18% GST. Currency conversion is also a taxable service; GST applies to its value determined under the tax rules, not to the entire remittance principal. The table uses an illustrative $1,000 receipt, ₹83 benchmark, ₹81.34 bank rate, $20 intermediary deduction and ₹500 processing fee.
| Fee Layer | Who Charges It | Illustrative Amount (USD or INR) | Visibility on Credit Advice |
|---|---|---|---|
| Sender's bank SWIFT/wire fee | Sender's (foreign client's) bank | Assume $25, paid separately by sender; no recipient deduction | Sender's payment confirmation |
| Correspondent/intermediary bank deductions | Correspondent/intermediary banks | Assume $20 deducted, leaving $980 for conversion | May require a payment trace |
| Beneficiary bank forex markup | Beneficiary (Indian) bank | Assume 2% below ₹83: ₹81.34/USD; spread cost ₹1,626.80 on $980 | Embedded in applied exchange rate |
| Bank processing fee and GST | Beneficiary (Indian) bank | ₹500 fee + ₹90 GST; ₹143.48 GST on conversion under Rule 32(2)(b); net credit ₹78,979.72 | Bank debit advice or tax invoice |
⚠️ COMMON MISCONCEPTION
OUR instructs that the sender bears transfer charges; SHA shares charges, and BEN puts them on the beneficiary. OUR is intended to prevent transfer-fee deductions from the principal, but confirm whether the bank guarantees full-value delivery. It does not remove currency-conversion costs.
If a payment arrives short, ask the client for their bank’s payment confirmation and request a trace. This can help identify deductions made before the funds reached your bank.

How Much Does a $5,000 Inward Remittance Actually Cost an Indian Freelancer?
In this illustrative $5,000 example, the recipient receives ₹4,04,028.63 instead of the ₹4,15,000 benchmark value, a difference of ₹10,971.37. This is a calculation using stated assumptions, not a typical bank quote.
Take Priya, a Bangalore-based user experience (UX) freelancer who invoices a US client $5,000. Assume a benchmark rate of ₹83 per dollar, a bank rate 2% lower, and these charges:
- Sender bank SWIFT fee: assume $25 paid separately by the client, so it does not reduce Priya’s $5,000 invoice payment.
- Intermediary bank deduction: assume $20 under a shared-charge arrangement, leaving $4,980 to convert.
- Beneficiary bank forex markup: at ₹81.34 per dollar, 2% below the assumed ₹83 benchmark, $4,980 converts to ₹4,05,073.20.
- Bank processing fee and GST: deduct ₹500 plus ₹90 GST on that fee, and ₹454.57 GST on conversion using the optional slab valuation under Rule 32(2)(b).
- Final INR credited: ₹4,04,028.63 is credited to her bank account. Against the ₹4,15,000 benchmark, Priya’s total difference is ₹10,971.37. The client’s separate $25 fee is not included.
The forex spread applies to the foreign currency actually converted, here $4,980 after the intermediary deduction. It should not be calculated as though the full $5,000 were converted.
In this example, the exchange-rate spread costs ₹8,266.80: $4,980 × (₹83 − ₹81.34). It is the largest cost in the example, even though it is embedded in the exchange rate rather than charged separately.
Through Skydo’s Global Bank Account route, Priya would pay $29 plus 18% GST on that fee, or $34.22 equivalent. Skydo advertises zero forex markup. Supported local collection avoids SWIFT collection fees, but sender-bank or SWIFT-route deductions may still apply, so check the route when comparing hidden charges.
✅ PRO TIP
Compare your bank’s applied rate with a market benchmark at the same conversion time. The Financial Benchmarks India Private Limited (FBIL) daily reference rate is a useful cross-check, but a daily rate difference can also reflect timing and market movement, not just markup.
How Do Hidden Inward Remittance Charges Affect Your FIRC and GST Compliance?
Charges on inward remittances can make your net bank credit lower than the invoice value. Reconcile the invoice, bank credit advice and Foreign Inward Remittance Certificate (FIRC) or equivalent remittance record, with evidence of fees. A difference alone does not establish a GST or export-compliance breach.
A FIRC or equivalent advice can show the foreign-currency receipt, conversion details, charges and net INR credit separately. Do not assume that its reported remittance amount always equals the final bank credit; check the fields and the issuing bank’s records. For routine export payments, a provider may supply a remittance advice rather than a FIRC.
- GST zero-rating: Export-of-services status depends on the conditions in the Integrated Goods and Services Tax (IGST) Act, including receipt in convertible foreign exchange or Indian rupees where permitted by the Reserve Bank of India (RBI). Document bank deductions and reconcile any difference rather than treating every short credit as a loss of zero-rating.
- GST reconciliation risk: If the invoice is $5,000 and the remittance received is $4,960, retain evidence explaining the $40 deduction. A documented bank fee is different from an unpaid invoice balance; ask your bank and tax adviser how to record the difference.
- EDPMS closure: Under RBI rules effective October 1, 2026, authorized dealer (AD) banks update or close Export Data Processing and Monitoring System (EDPMS) entries for goods and services. For shipping bills or service invoices up to ₹10 lakh, closure may be based on the exporter’s declaration of realization, with quarterly bulk declarations also permitted. Ask your AD bank to account for documented fees and follow the applicable export-declaration requirements. Use the correct purpose code for inward remittances.
The compliance guideline for inward remittance covers these requirements in more detail.
💡 QUICK INSIGHT
Keep the invoice, remittance advice, fee details and bank credit together. These records help you and your bank explain a short credit without confusing bank charges with unpaid export proceeds.
Save the credit advice, FIRC or equivalent remittance record, and invoice together when each payment arrives. Add the bank’s explanation of any deductions so the reconciliation is ready if a query comes later.
How Does Skydo Eliminate Hidden Charges on Inward Remittance?
Hidden charges can come from several parties in the payment chain. The total cost of a traditional SWIFT receipt depends on the banks, route, negotiated exchange rate and charge instruction, so there is no single percentage that applies to every transfer.
Skydo offers disclosed transaction fees, zero forex markup and automatic remittance advice. Supported local collection routes avoid SWIFT collection fees, but sender-bank charges or SWIFT-route deductions can still apply.
- Pricing: For Global Bank Account payments, Skydo lists $19 up to $2,000, $29 from $2,001 to $10,000, and 0.3% above $10,000, plus 18% GST on the transaction fee. There are no monthly fees. Other products can have different pricing; check the applicable quote.
- No forex markup: Skydo advertises live foreign exchange (FX) conversion with zero markup. An earlier displayed rate is not a guaranteed locked rate; the applied rate depends on conversion timing.
- Local collection accounts: Skydo provides free virtual receiving details for supported local payments in currencies including USD, EUR, GBP, SGD, AUD and CAD. Use the account matching the payer’s country and currency. Supported local collection avoids SWIFT fees on that leg; International SWIFT account payments may still incur deductions.
- Automatic FIRA: Skydo automatically provides a free Foreign Inward Remittance Advice (FIRA) for each settled international payment, available from the dashboard. Keep it with the invoice and fee/GST record for reconciliation; it does not replace every GST or Directorate General of Foreign Trade (DGFT) requirement.
- EDPMS and eBRC support: Skydo offers EDPMS closure assistance and electronic Bank Realisation Certificate (eBRC) generation assistance. Exporters can link their DGFT account, bulk-upload shipping bills and map Inward Remittance Messages (IRMs) to generate eBRCs. Only the authorized dealer bank can close the EDPMS entry.
- Settlement: Timing depends on the currency, route and compliance checks. Skydo’s terms provide for efforts to credit funds within one to three business days after successful screening and compliance checks. The payer-to-collection-account leg takes additional time.
- Setup: Setting up Skydo takes about 10–15 minutes, subject to document and identity checks; activation may take longer if manual verification is needed.
What is the typical total charge on an inward remittance in India?
There is no single typical charge that applies to every inward remittance. Compare the sender’s fee, any intermediary deductions, your Indian bank’s processing fee, the exchange-rate spread and GST. The charge instruction and currency route affect who pays each fee.
Does choosing OUR charges mean I receive the full invoice amount?
Why is the amount on my FIRC lower than what my client paid?
Are SWIFT charges on inward remittance fixed?
What is a forex markup and how does it differ from a fee?
How can I calculate how much was actually deducted from my inward remittance?
Does GST apply to inward remittance bank charges?
How does Skydo's flat fee compare with traditional bank charges on a $5,000 remittance?