logo

How to Receive Money From the US to India?

There are eight ways to receive international payments from the US to India: bank wires, PayPal, Wise, Payoneer, Airwallex, Stripe, remittance services, and virtual multicurrency accounts like Skydo. Each works differently on speed, fees, and compliance. Which one fits comes down to what you are being paid for and how often. Here is the lowdown.
Accept payment from 150+ countries
USD

Client pays

1 USD = 95.7300 INR

Estimated fx rate
You'll receiveINR
Skydo

₹4,75,374

Banks

₹4,66,952

You lose:1.8% ↓

PayPal

₹4,34,652

You lose:8.6% ↓

100+ reviews
Trusted by 50,000+ businesses
Over $1B processed • Licensed by RBI
DBSVISAHDFC BankCurrencycloud
RBI PA-CB authorisedApproved under
RBI's PA-CB framework

Here's a Quick Comparison Table on the Top Ways to Receive Money From USA to India

Bank wires, PayPal, Wise, remittance services, and Skydo, compared against six factors that matter the most: fees, FX markup, settlement time, FIRA, regulatory status, and support.
FactorsBankPayPalWiseRemittanceSkydo
FeesWire charge plus correspondent and receiving charges4.4% + fixed fee~1.6-1.8% + $2 per FIRAService fees, up to 5 to 10% all inFlat $19 / $29 / 0.3% by slab
FX markup2 to 4%~4%0%, mid-marketBuilt into the rate0%, mid-market
Settlement time3 to 7 days~24 hoursWithin 1 day~1 dayWithin 24 hours
FIRAManual, chase bankWeekly digital$2 per FIRANot issuedInstant and free
Regulatory statusAD Category-I bank, RBI regulatedIn-principle PA-CB approvalFull PA-CB-I authorisationConsumer rails, not for businessRBI authorised PA-CB
SupportBranch hoursEmail, slowPhone, email & chatAgent or app supportIndia-based, dedicated

Detailed Comparison on Ways to Receive Money from the US in India

There are multiple ways in which a client from the US can pay you. Here's a deep dive into how each one works, and what it costs you, so you can pick the one that keeps the most in your account.
Bank Wire Transfer (SWIFT)SWIFT transfer is the traditional banking route for receiving money from a client abroad, using your bank account number and SWIFT code. The sender’s bank routes the funds through the SWIFT network, often via multiple correspondent banks, before crediting your Indian account, and Indian banks typically apply a forex markup along the way, for example crediting you at ₹92/USD instead of the actual ₹94/USD.
Pros
Connects to virtually any bank globally, works for any currency pair
No eligibility checks or approval needed on the client’s end to send
Cons
1–3% worse forex rates vs mid-market
Possible intermediary bank deductions ($10–$40)
Slow settlement (3–7 business days)
Cost$15–50 sender/intermediary fees + FX markup + paperwork charges
Settlement Time3–7 business days
FIRANot automatic, request separately from your AD bank at an added cost
Ideal ForLarge transfers by established businesses prioritising safety

Six Factors to Consider While Receiving Money From the US to India

Total cost, banking rails, settlement speed, FIRA & compliance, customer experience, and support quality are the top 6 factors you need to consider before choosing how to receive money from the US.
Total Cost, Not Sticker FeeBanks and gateways hide 2-4% FX markup on US payments. Compare the INR received, not the stated fee.
Look forMid-market rates + flat pricing
US Bank & Rail CoverageA platform that doesn't support ACH and Fedwire makes collections harder.
Look forACH and Fedwire acceptance across US banks
Settlement Speed3-5 business day settlements on US wires can slow your cash flow.
Look for<24h to your Indian bank
FIRA & ComplianceManual FIRA requests and extra certificate fees can quickly add up.
Look forAuto-issued FIRA per payment
Client ExperienceA complicated payment flow makes your US client slower to pay.
Look forLocal US account details for your client
Support QualitySlow, email-only global support can delay critical payment issues.
Look forIndia-based phone & WhatsApp

Why Indian Businesses Prefer Skydo to Receive Money from the US to India

Skydo is built ground-up for Indian businesses getting paid by international clients. Transparent pricing, mid-market FX, and compliance handled the way exporting from India actually works.
Receive Payments from the US, Like a Local
RBI authorized and ISO 27001
24 hour settlement. Best India support
Currency supported

150+ currencies

Flat fees
Under $2,000$19
$2,001-$10,000$29
Above $10,0000.3%
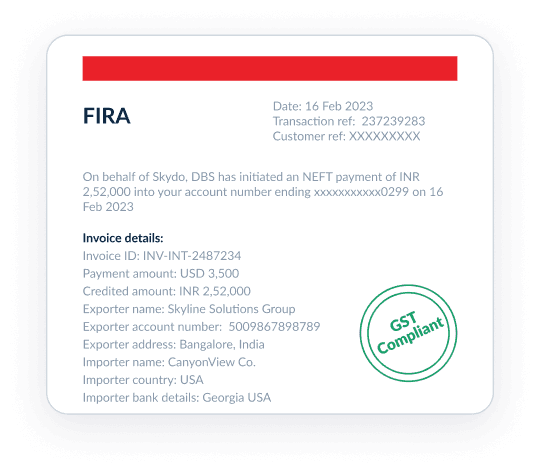
Instant & free FIRA,every time.GST-compliant FIRA, downloadable from your dashboard, free.

How to Receive Payments from the US using Skydo in 3 Simple Steps

Step 1
Sign up in 5 minutesShare your PAN, Aadhaar number, and Indian bank details. Get a virtual US account instantly.
Step 2
Share Account DetailsYour client pays into the virtual US account using domestic transfer methods like ACH. No charges on their end.
Step 3
Receive INR in 24 hoursSkydo converts at the live mid-market rate and settles INR to your Indian bank. So what you see is what you get.
From sign-up to your first international payment landing in INR, under a week, every time.

How Your US Client Pays You Using Skydo

With Skydo, your US client isn't sending an international transfer. They're paying into local US account details, the same way they pay any US vendor. Here's how the money leaves their account.
ACH (Local Transfer)Your client enters your US account routing number and account number in their bank or accounting tool, the same details they'd use to pay a local US vendor. The payment moves over the ACH network.
Cost to your clientFree or a few cents at most US banks.
Speed1 to 3 business days.
Best forMost invoices. The default, low-cost way US clients pay.

Save More While Receiving Money from the US to India with Skydo

Move the slider to your invoice amount and see exactly what you keep with Skydo, versus what a bank, PayPal, Stripe, or Wise leaves you with.
USD
Client pays
Payment partner
Save ₹28,889 on this payment with Skydo!1 USD = 95.73 INR · estimated mid-market rate

Watch How Skydo Helps You Receive Money from the US to India

See how Indian businesses get paid by US clients on Skydo, from sharing account details to INR landing in the bank, in one short walkthrough.

Here’s What Skydo Users Have to Say About Receiving Payments from the US

Indian businesses getting paid by US clients on Skydo, in their own words.
Tarun Shah video thumbnail
Chetanya video thumbnail
Varun video thumbnail
50K+Customers onboarded
200K+Payments processed annually
4.8+Average rating
Skydo is authorised by the Reserve Bank of India as a Payment Aggregator, Cross Border (PA-CB). Your money moves through a regulated channel, every time.

Common Questions About Receiving Money from the US to India

How can I receive money from the US to India?

You can receive US payments through a bank wire (SWIFT), a gateway like PayPal or Stripe, a remittance service, or a virtual multicurrency account. A virtual account is usually the cheapest and fastest, because your US client pays into local US account details and you receive INR at the mid-market rate. Skydo gives you a virtual US account so clients can pay you like a local US transfer.

What is the cheapest way to receive money from the US to India?

The cheapest option is the one with the lowest total cost, not the lowest headline fee. Gateways can cost 4 to 5% once you add the FX markup, which quietly eats more than a flat fee would. A flat-fee platform on the mid-market rate keeps more of every US invoice. On a $10,000 payment, Skydo costs a flat $29 with zero FX markup.

How long does it take to receive a payment from the US in India?

It depends on the method. A US bank wire (SWIFT) can take 3 to 7 business days, and some gateways hold funds longer. A virtual multicurrency account is faster, usually settling into your Indian bank within 24 hours. With Skydo, most US payments reach your account within a day.

How does my US client actually pay me?

Your US client pays into local US account details using ACH for most payments, or Fedwire for larger or urgent ones. For them it works exactly like paying any US vendor, no SWIFT, no international transfer form, no foreign wire fee on their end.

Is there a limit on how much money I can receive from the US?

There is no official upper cap on inward remittances to India, so you can receive as much as your client sends. Large transfers can trigger extra compliance checks, and your bank or platform may ask for more documentation to satisfy RBI and anti-fraud rules. Individual platforms also set their own ceilings, and payments routed through an RBI-authorised cross-border payment aggregator carry a per-transaction cap under the PA-CB framework, so check before you raise a large invoice.

Can I receive USD in my Indian bank account?

Not as USD. Under RBI rules an ordinary Indian savings or current account cannot hold foreign currency, so incoming dollars are converted to INR before they credit, at whatever rate your bank applies. Holding foreign currency needs a special account such as an EEFC (Exchange Earners' Foreign Currency) account, which comes with conditions and is uncommon for freelancers and small businesses. A virtual US account is the practical alternative: your client pays in USD, and you receive INR at the mid-market rate.

What documents do I need to receive payments from the US in India?

Four things. Your PAN, which your bank needs to record any foreign remittance credit, plus Aadhaar or a passport for identity. Your Indian bank account number with the IFSC code, and the SWIFT or BIC code if the money is arriving as a wire. The correct RBI purpose code for what you are being paid for, since a software consulting export sits under a different code from goods. And a FIRA for each payment, which is the document your CA will ask for at filing.

Do I need a SWIFT code to receive money from the US?

Yes, if the payment is arriving as a bank wire. Your client's bank needs the SWIFT or BIC code of your Indian bank to route it, along with your account number and IFSC. If your client pays into local US account details instead, the payment never touches SWIFT and no code is needed on either side.

Do I get a FIRA for payments received from the US?

Yes. A FIRA (Foreign Inward Remittance Advice) is your proof that a US payment came in legally, and your CA needs it for GST and FEMA compliance. Many banks make you request it manually and charge per certificate. With Skydo, an e-FIRA is generated automatically on every US payment and stored in your dashboard, ready to download.

Do I have to pay tax on payments received from the US?

GST does not apply. Services exported and paid for in foreign currency are zero-rated under Indian GST law, so you do not charge your US client GST. Income tax does apply. The earnings are added to your total income and taxed at your slab rate as an Indian tax resident, with no special exemption for foreign income.

How much are the fees to receive money from the US to India?

Fees depend on the method. Banks add a wire charge plus a 2 to 4% FX markup, and PayPal can run to 4 to 5% all in. Skydo charges a flat fee with zero FX markup: $19 under $2,000, $29 from $2,001 to $10,000, and 0.3% above $10,000, so what you see is what you get.

Is PayPal a good option for US to India transfers?

It is convenient, and US clients already trust it, which is why most freelancers start there. Cost is the catch. PayPal charges 4.4% plus a fixed fee and adds roughly 4% on currency conversion, so the all-in cost can approach 8% of the invoice. You also get a weekly digital statement rather than a FIRA on each payment, which makes reconciliation harder at filing time.

Can I track my payment from the US?

For a bank wire, ask your client for the MT103 from their bank. It is the confirmation document for the transfer and lets you trace where the money is in the correspondent chain. With Skydo you can track the payment in your dashboard in real time, without asking your client for anything.

Is it safe and legal to receive money from the US to India through Skydo?

Yes. Skydo is authorised by the Reserve Bank of India as a Payment Aggregator, Cross Border (PA-CB), so your money moves through a regulated channel every time. You get a FIRA on every payment and funds settle directly to your Indian bank account.

Ready to Save More on International Payments?

Start receiving global payments with Skydo and keep more of what you earn.